Key Takeaways
- Coastal homes can provide access to beaches, views, and outdoor recreation, but may require closer attention to insurance, weather exposure, and exterior maintenance.
- Inland homes can offer more space, privacy, and flexible floor plans, though the drive to the coast and other destinations may be longer.
- Compare taxes, insurance, utilities, repairs, association dues, and commuting costs alongside the purchase price.
- Review flood exposure, drainage, roof condition, access routes, and insurance availability before making a final decision.
- Neighborhood-level research matters because nearby Santa Barbara County communities can have very different conditions and conveniences.
Table of Contents
- Introduction
- Put Location Before Floor Plans
- What Coastal Homes Can Offer
- What Inland Homes Can Offer
- Compare Full Ownership Costs
- Review Flood, Fire, and Weather Factors
- Test the Daily Routine
- Consider Long-Term Appeal
- Use a Side-by-Side Worksheet
- Final Buyer Checklist
Choosing between a coastal and inland home in Santa Barbara County is about much more than the listing price. Buyers may be deciding between beach proximity in Montecito or Carpinteria, a hillside setting near Santa Barbara, or more land and privacy in the Santa Ynez Valley. For a street-level perspective, Montecito real estate agents at Alemann & Associates offer local luxury-home expertise across Santa Barbara County, including Montecito, Hope Ranch, Carpinteria, Goleta Valley, and the Santa Ynez Valley. Their website includes property search tools and local-area resources that can help buyers compare location, home features, and neighborhood tradeoffs.
A smaller home close to the coast can be an excellent fit for someone who values ocean access, walkability, and a shorter drive to favorite restaurants. A larger inland property may better suit a buyer who wants room for guests, gardening, hobbies, or a quieter daily routine. The best choice is the one that works after the excitement of the showing has passed.
Put Location Before Floor Plans
A beautiful kitchen or dramatic view does not solve a location mismatch. Before touring seriously, identify your three highest priorities. They might be a manageable commute, beach access, a large yard, proximity to schools, privacy, or easy access to medical care and shopping. Then evaluate every property against those priorities.
In Santa Barbara County, a few miles can change traffic patterns, road conditions, lot sizes, noise levels, temperatures, and access to services. A buyer who wants to walk to the coast may accept a smaller lot. Another buyer may prefer an inland home with a detached office, extra storage, and room for outdoor projects.
What Coastal Homes Can Offer
Coastal living can place beaches, ocean views, trails, and outdoor dining closer to everyday life. In areas such as Montecito and Carpinteria, however, “coastal” can mean very different things. A home may be on the waterfront, near the beach but separated by roads or rail lines, or simply positioned to capture a distant view.
RelatedDesigning Homes With Character: How the Right Details Bring a Space to Life
Price those features separately. Direct access, an unobstructed view, elevation, parking, road access, and usable outdoor space each affect how a home feels and functions. Buyers should also inspect exterior materials, windows, drainage, landscaping, and the roof’s condition because wind, moisture, and salt air can increase maintenance needs over time.
What Inland Homes Can Offer
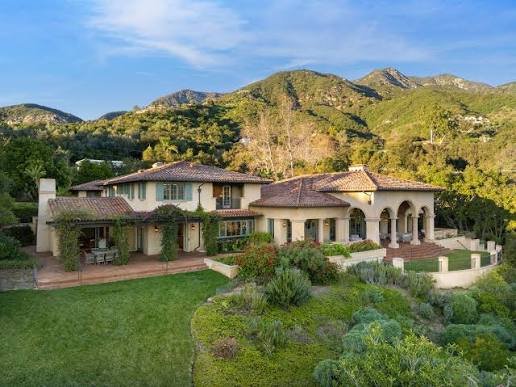
Inland communities may provide larger lots, wider floor-plan choices, quieter streets, and greater flexibility for gardens, guest accommodations, workshops, or home offices. Inland does not automatically mean isolated. Depending on the community, a home can still be convenient to schools, parks, shopping, and major routes.
RelatedPressure Testing Safety in Houston, TX: A Practical Checklist for Industrial Teams
Property-specific diligence still matters. Review drainage and slope conditions, tree maintenance, road access, utility connections, and whether the property uses a well or septic system. Buyers considering foothill, rural, or valley locations should also understand the home’s wildfire exposure and emergency access.
Compare Full Ownership Costs
A lower purchase price does not always produce a lower monthly cost. A property with higher insurance premiums, larger maintenance demands, association obligations, or a lengthy commute may cost more to own than a higher-priced alternative.
RelatedWhy Modern Water Coolers Are Becoming a Smarter Choice for Homes and Workplaces
Build a realistic property budget
- Mortgage payment, property taxes, and homeowners’ association dues.
- Homeowners insurance, plus flood, earthquake, or wildfire coverage when applicable.
- Utilities, including heating, cooling, water, internet, and irrigation.
- Roof, exterior, pest control, landscaping, and drainage maintenance.
- Expected repairs and replacements for major systems and appliances.
- Fuel, vehicle wear, parking, and time associated with commuting.
Review Flood, Fire, and Weather Factors
Start with the exact address, not general assumptions about a neighborhood. Buyers can use the official flood hazard information for an address to review FEMA mapping, then discuss the results with qualified insurance and real estate professionals. Flood maps are one tool, not a substitute for inspection, disclosure review, or insurance guidance.
Request insurance quotes before removing important contingencies, especially for homes near the coast, in foothill areas, or on larger rural parcels. California buyers can also review the state guidance on residential insurance coverage to better understand common policy questions and exclusions.
RelatedWhy Water Treatment Matters More Than Ever for Homes, Businesses, and Growing Communities
- Check the current flood zone information and ask whether an elevation certificate is available.
- Review the roof’s age, material, condition, and visible wind-resistance features.
- Ask about prior water intrusion, storm damage, smoke damage, or drainage work.
- Confirm evacuation routes, emergency access, and driveway conditions.
Test the Daily Routine
Visit more than once a day. Drive the route to work, school, grocery stores, medical care, and the airport during realistic conditions. Check parking, street lighting, sidewalk access, mobile service, and internet options if remote work is important. In communities with seasonal visitors, ask whether nearby services and traffic patterns change with the seasons.
Consider Long-Term Appeal
Future appeal depends on practical details as well as a desirable setting. Parking, storage, flexible bedrooms, usable outdoor areas, and straightforward access can matter to many future buyers. Insurance availability and ongoing ownership costs may also influence who can comfortably consider a property. Review recent comparable sales from the same neighborhood and property type rather than relying on broad market headlines.
RelatedWhy More Homes and Businesses Are Choosing Bottleless Water Systems Over Bottled Water
Use a Side-by-Side Worksheet
- Coastal property: Record asking price, beach or water access, parking, view quality, insurance quote, exterior condition, traffic, and seasonal activity.
- Inland property: Record lot usability, privacy, commute time, utility setup, drainage, vegetation management, insurance quote, and nearby services.
- For both homes: Note repair needs, association rules, planned assessments, disclosures, inspection findings, and the features that support your daily routine.
Final Buyer Checklist
- Set a complete monthly ownership budget.
- Define the lifestyle features that matter most.
- Compare coastal and inland homes using the same criteria.
- Review flood, fire, weather, drainage, and insurance considerations.
- Test the commute and local services during normal hours.
- Inspect the roof, foundation, exterior, and major systems.
- Read association documents and confirm any planned assessments.
- Choose the location that supports your actual life, not only your ideal weekend.
Neither coastal nor inland living is automatically better in Santa Barbara County. A careful comparison of costs, risks, convenience, maintenance expectations, and long-term plans can help you choose a home that remains a strong fit well beyond move-in day.